Development & Commercial
Commercial Property Loans
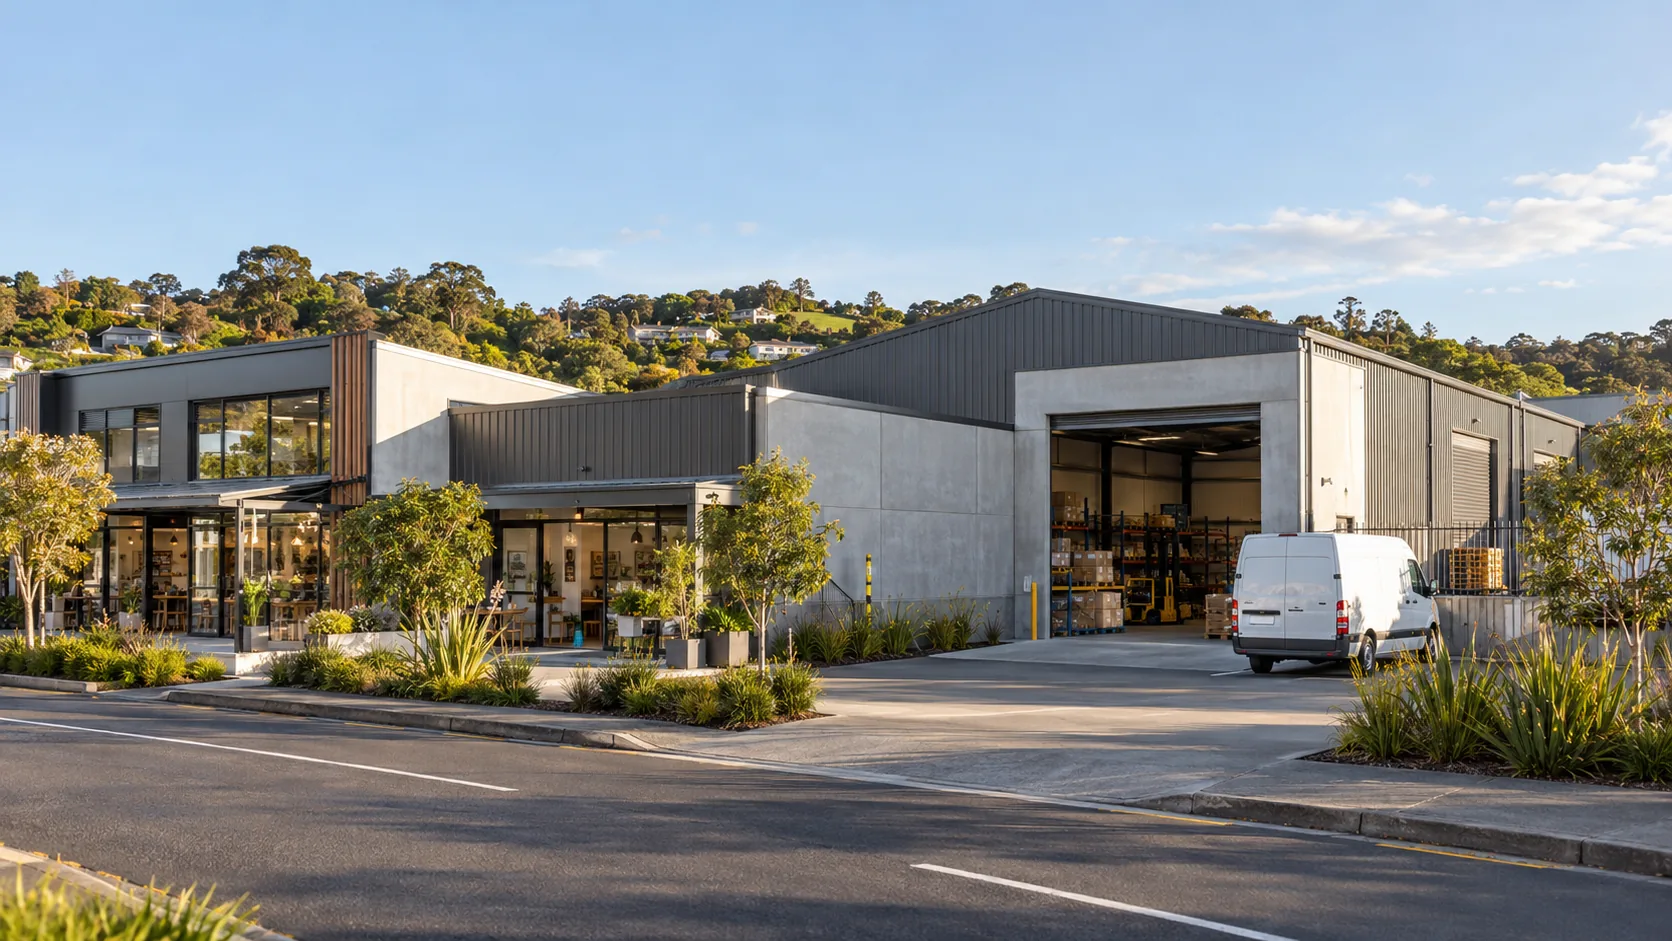
Purchase or refinance retail, office, industrial or mixed-use property. Build a robust, sustainable financing structure secured by the asset and supported by its lease profile.
Talk To An Expert
What is a commercial property loan?
A commercial property loan is a mortgage specifically used to purchase, refinance, or develop commercial real estate. Unlike a general business loan, it is secured against the commercial property being purchased or refinanced. Eligible property types may include:
Office Properties:
Loans for office buildings used by professional services, corporate tenants, or mixed-use occupiers.
Industrial Properties:
Warehouses, factories, and logistics facilities used for storage, manufacturing, or distribution.
Retail Properties:
Shops, cafés, and retail centres generating rental income from trading businesses.
Development Sites:
Vacant or underutilised land intended for commercial or mixed-use development projects.
Specialist Assets:
Hotels, motels, medical centres, vineyards, and other niche commercial properties.
Who it's for
Individuals or entities looking to purchase or refinance retail, office, industrial, or mixed-use property.
Yield-focused investors seeking stable rental cash flow and a long-term hold.
Owner-occupiers aiming to enhance business stability and capital allocation through owning their premises.
What lenders look at
Location:
Pricing can differ by property type — retail, industrial, office, or mixed-use — and by micro-location fundamentals.
Lease quality:
Remaining lease term, weighted average lease term (WALT), tenant covenant strength, rent review clauses, and vacancy risk.
Valuation:
An independent registered valuation may be required. A professional valuer assesses market value to support lending and pricing decisions.
LVR:
Commercial LVRs are generally lower than residential. Many lenders expect 30–35% equity, meaning maximum lending is often around 65–70% of the property value, subject to the asset type, lease strength, and borrower profile.
%NBS:
The earthquake strength of the building is a critical factor, especially in New Zealand. Lenders generally prefer a rating of at least 67% of the New Building Standard (%NBS).
Questions & Answers
01Does a %NBS rating prove that a building is "safe"?
No. %NBS is a relative indicator of seismic performance against the New Building Standard for that site/use. It is not a warranty or certificate of safety, nor a guarantee the building won't suffer damage in an earthquake.
02Can I use a commercial property loan to buy a home?
No. Commercial loans are intended for business/commercial use. They can't be used to purchase a personal residence.
03Are commercial property loan interest rates usually higher than home loan rates?
Generally yes. Lenders view commercial property as higher-risk than standard residential lending, so pricing is typically higher and more dependent on the asset type, lease strength and overall structure.
04How does LVR affect my deal?
A more conservative Loan-to-Value Ratio (LVR) typically leads to more favourable terms and a higher likelihood of approval. A higher LVR usually attracts tighter conditions (e.g., extra security/covenants) and higher pricing.
Start Your Journey
Need Extra Funds?
Talk to us today about how a commercial property loan could support your purchase, refinance, or investment goals.